VA home loans · Greater Seattle
The VA buyer's playbook.
Who qualifies, what a VA loan can buy, how the VA appraisal works and what to expect from contract to keys, sourced from the U.S. Department of Veterans Affairs and explained by Brian Huie, a U.S. Air Force veteran and Principal Broker and Realtor at Compass.
At a glance
What the VA benefit gives you
- No mortgage insuranceNo PMI or MIP, the monthly insurance most low-down-payment loans add.
- No VA loan limitWith full entitlement, the VA sets no limit. The lender approves the amount and the appraisal caps it.
- Seller-paid closing costsVA does not limit seller credits for closing costs. Other seller concessions are capped at 4% of the home's reasonable value.
- Reusable and assumableUse the benefit again after selling or refinancing. VA loans can be assumed, with no penalty for paying one off early.
Who qualifies
Check your VA eligibility in about a minute
Eligibility comes down to service time and a Certificate of Eligibility (COE). Answer a few questions for a quick read, or skip to the full rules.
Eligibility check
Service requirements, in one table
| Active duty | At least 90 continuous days of service. |
|---|---|
| Veterans, Gulf War era (Aug. 2, 1990, to present) | At least 24 continuous months, or the full period called to active duty (at least 90 days). |
| National Guard | At least 90 days of non-training Title 10 active duty; or 90 days of active duty including 30 consecutive days under Title 32 (sections 316, 502, 503, 504 or 505); or 6 creditable years. |
| Selected Reserve | At least 90 days of non-training active duty, or 6 creditable years. |
| Surviving spouses | Eligible for or receiving certain Dependency and Indemnity Compensation (DIC), or the spouse of a service member who is missing in action or a prisoner of war. |
Earlier service periods and service-connected disability exceptions have their own rules on VA's eligibility page. The COE can be requested online, through the lender, or by mail with VA Form 26-1880.
Contract to keys
How a VA purchase unfolds
You and your lender
COE and pre-approval
The lender confirms eligibility and entitlement and sets the real budget before the first tour.
Brian
Search the right homes
A VA loan can buy a home of up to 4 units that you will live in, or a condo in a VA-approved project. Brian checks a building's status in VA's condo search before a tour, not after an offer. More on VA condo approval and townhomes and HOAs.
Brian
Write an offer listing agents trust
Brian explains the VA appraisal and terms to the listing agent before offers are compared, and asks for seller credits where the market allows.
VA appraiser
The VA appraisal
If the value looks likely to come in below the price, the appraiser gives the buyer's side 2 business days to send more sales data (VA's Tidewater procedure). After the Notice of Value, a reconsideration can be requested, and VA staff review it within 5 business days.
You, your lender and Brian
Repairs and closing costs
The home must meet VA's minimum property requirements. Some listed repairs can be waived with the lender's agreement if the home stays safe, structurally sound and sanitary. Only the VA funding fee can be financed into the loan; other costs are paid at closing or covered by seller credits.
You
Close and move in
A VA purchase loan is for a home you live in, so plan the move-in as part of the timeline.
Myths
What some listing agents still believe
"A low VA appraisal kills the deal."
The Tidewater procedure gives the buyer's side 2 business days to support the price before the value is final, and a reconsideration is available after.
"Every repair on the list has to be fixed."
Some minimum property repairs can be waived with the lender's agreement, as long as the home is safe, structurally sound and sanitary.
"VA buyers make the seller pay everything."
Seller credits are negotiated like any offer. Concessions beyond closing costs are capped at 4% of the home's reasonable value.
Listing agent or seller? Selling to a VA buyer covers the appraisal, required repairs and seller credits on one printable page.
Funding fee
The one VA fee, and who skips it
Most VA buyers pay a one-time funding fee, which can be financed into the loan. It is lower with a larger down payment and higher after first use; VA publishes the current chart on its funding fee page, and the lender quotes the exact amount.
No funding fee applies, for example, to buyers receiving VA compensation for a service-connected disability, surviving spouses receiving DIC, and active-duty members who show a Purple Heart on or before closing.
FAQ
Common VA buyer questions
Can a VA loan buy a condo in Seattle?
Yes, if the building is a VA-approved project. Status can be checked in VA's condo search, and Brian checks it before a tour. The VA-approved condo list on this site updates weekly.
Is there a VA loan limit in King County?
With full entitlement, the VA sets no loan limit; the lender approves the amount and the appraisal caps it. With part of the entitlement already in use, the remaining amount is based on the county loan limit.
Can the seller pay the buyer's closing costs?
VA does not limit seller credits toward closing costs. Other seller concessions are capped at 4% of the home's reasonable value shown on the VA Notice of Value.
Can a VA loan buy a duplex or fourplex?
A VA purchase loan can buy a home of up to 4 units, as long as the buyer lives in it.
Can the VA benefit be used more than once?
Yes. The benefit can be used again after selling or refinancing. The funding fee is higher after first use unless the buyer is exempt.
Does Brian charge VA buyers anything extra?
No. VA buyers get the same strategy, preparation and negotiation as every client. How the buyer's broker is paid is set in the written buyer agreement.
Talk it through with a veteran broker.
A free 30-minute consult with Brian. Eddie Huynh at Movement Mortgage handles the loan.
Sources
- Eligibility for a VA home loan, U.S. Department of Veterans Affairs.
- VA-backed purchase loan, VA.
- VA home loan limits, VA.
- VA funding fee and loan closing costs, VA.
- VA appraisal policies (Tidewater, reconsideration of value, repair waivers), VA Loan Guaranty Service, Dec. 2021.
General information as of October 2026, not an offer of credit or legal advice. Eligibility and loan approval are decided by the VA and the lender.
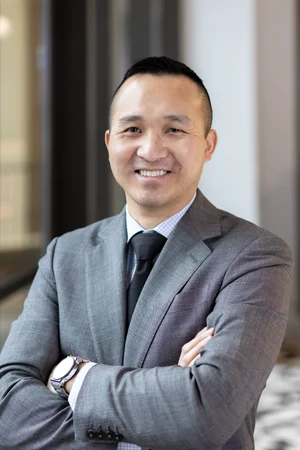
Brian Huie
U.S. Air Force veteran
Your VA plan, in one call.
A free 30-minute consult on eligibility, budget and the homes that fit. Pick a time right here, without leaving the page.
Pick a time Or send Brian a notePrincipal Broker and Realtor, Compass. Eddie Huynh at Movement Mortgage handles the loan side. No cost, no commitment.